How to Sell Your House Quickly in Florida: 2026 Guide
Editorial Team 14 min read
Table of Contents
- Why Selling Fast in Florida Takes More Than a Sign in the Yard
- How Long Does It Take to Sell a House in Florida?
- How to Price a House to Sell Quickly
- Repairs to Make Before Selling a House (and What to Skip)
- Home Staging Tips for a Quick Sale
- Cash Offer vs. Traditional Listing: Which Sells Faster?
- Florida Disclosures, Insurance, and Roof Rules Sellers Must Know
- Your Fast-Sale Checklist and Next Steps
- Frequently Asked Questions
Last Updated: October 19, 2026
Why Selling Fast in Florida Takes More Than a Sign in the Yard
If you want to know how to sell house quickly in Florida, start with the real numbers. Homes here average 66 days on the market, then another 34 days to close after an offer is accepted, according to List With Clever's Florida selling timeline data.
At Janet Fuller PA, we work with sellers across Volusia and Flagler counties who cannot always wait that long. A military relocation, a downsizing move, an inherited property: each one comes with a clock.
Below is the full playbook: pricing, repairs, staging, cash offers, and the Florida rules most guides skip. Speed is not one decision but a stack of small ones, and a single weak link slows the whole sale.
How Long Does It Take to Sell a House in Florida?
The short answer is about 66 days on market plus 34 days to close, based on 2026 statewide averages from List With Clever.
That timeline splits into two phases:
- Days on market: the time from listing to an accepted offer
- Days to close: the time from acceptance to funding
Timing also shifts with the season. Realtor.com named April 12-18 as the strongest listing week nationally in 2026, per Florida Realtors' coverage of seasonal listing patterns.
The takeaway: treat any timeline as a range, not a promise.
How to Price a House to Sell Quickly
Pricing is the fastest lever you control: price too high and your listing sits while interest cools; price right and you can pull multiple offers in the first two weeks.
Here is how we approach it:
- Pull comparable sales from the last 90 days, not the last year
- Adjust for condition, lot size, and upgrades
- Compare active listings to see what buyers will choose instead of you
- Set a price that lands in the top of your search bracket, not the bottom
A common mistake is chasing a neighbor's sale price from a stronger market. Buyers compare you to what is available today.
Reading Comparable Sales in Volusia and Flagler
Comparable sales are recent nearby sales of similar homes used to estimate market value. In our two counties, beachside and inland pricing diverge widely, so comps must come from the same pocket, not just the same ZIP code.
Watch for these traps:
- Comps from a different school zone
- Sales from before a rate shift
- Homes with pools or without them
We pull comps block by block, because a mile can change the number.
Repairs to Make Before Selling a House (and What to Skip)
Not every repair pays you back. Focus on items that show up in inspections or scare buyers off.
Do these:
- Fix active leaks and water stains
- Repair broken windows and doors
- Replace burnt-out fixtures and outlets
Skip these:
- Full kitchen remodels
- Luxury bathroom upgrades
- Pool additions
The middle ground is an as-is sale. You list without repairs, and buyers price the work into their offer.
Home Staging Tips for a Quick Sale
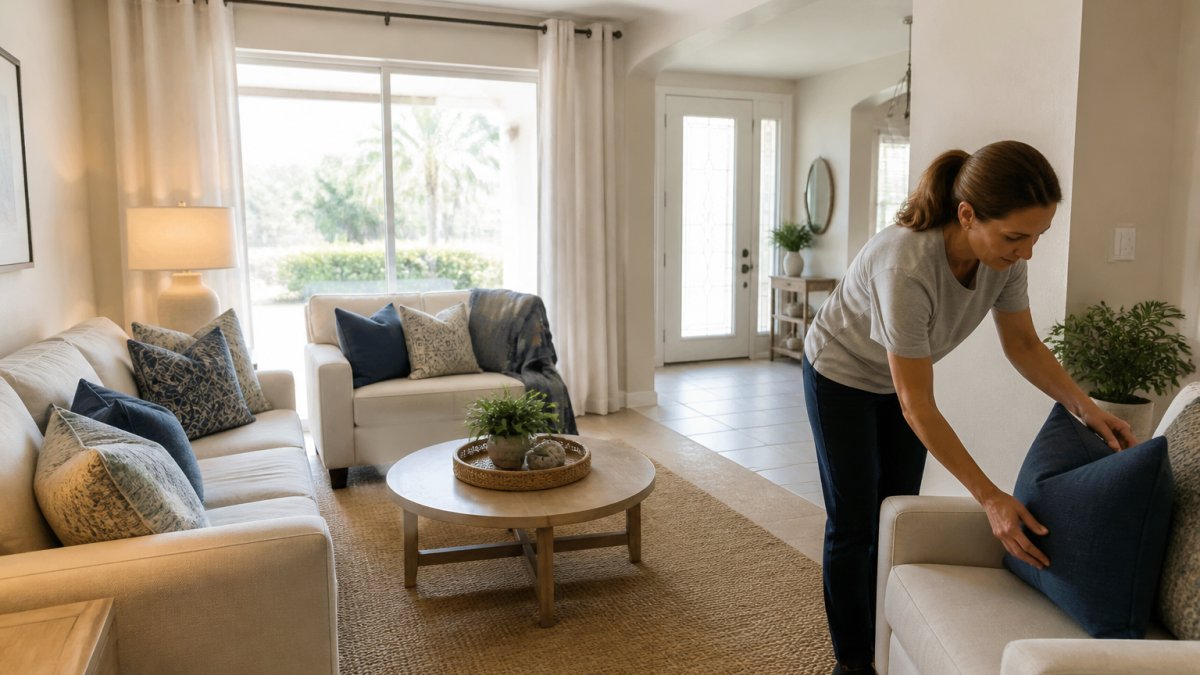
Staging helps buyers picture themselves in the home and photographs better, and most buyers see your listing online first.
Our staging checklist:
- Declutter every surface and closet
- Remove personal photos and religious items
- Deep clean windows, grout, and baseboards
Cash Offer vs. Traditional Listing: Which Sells Faster?
A cash offer sells faster on paper; a traditional listing usually nets more. The right choice depends on your timeline, equity, and how much of the gap you will trade for speed.
| Factor | Cash Offer | Traditional Listing |
|---|---|---|
| Typical timeline | Days to a few weeks | About 100 days (66 on market + 34 to close) |
| Repairs | Usually none | Often required after inspection |
| Showings | None | Multiple |
| Sale price | Typically below market | Market-driven |
| Financing risk | None | Appraisal and loan risk |
| Fees | Varies by buyer; often no agent commission | Agent commission applies |
| Closing costs | Often paid or split by buyer | Seller pays customary closing costs |
HomeLight states its cash sale platform can close in as few as 7 days, though that is a service claim rather than an independent benchmark. Compare any cash offer against a realistic net proceeds estimate from a listing before you sign.
Net Proceeds: The Comparison Most Guides Skip
Speed has a price, and the only honest comparison between a cash offer and a listing is a net proceeds worksheet: same inputs, different values.
What comes out of the sale price:
- Agent commission. A traditional listing typically carries a listing-side commission plus a buyer-side commission, both negotiable. A cash buyer often charges none, but confirm in writing.
- Seller closing costs. Title, settlement, recording, and doc stamps are customary seller costs on a listing. Some cash buyers absorb these; some do not.
- Repairs and concessions. A listing usually requires inspection repairs or a credit to the buyer. A cash offer typically requires neither, but the discount is already baked into the price.
A common pattern: the cash offer looks lower on the headline number but closes the gap once repairs, concessions, commissions, and three months of carrying costs are subtracted. Sometimes it does not, put both columns on one page to know.
Verifying a Cash Buyer Before You Sign
"Cash" is a claim until documented. Before you commit:
- Ask for proof of funds from a verified financial institution, dated within the last 30 days. A screenshot is not proof; a letter or statement with the institution's contact information is.
- Read the contract for assignment clauses. Some buyers contract to sell your home to a third party before closing. That is legal, but it changes who shows up at the table and can delay the deal.
- Confirm who holds earnest money and where it is deposited. It should sit with a title company, attorney, or licensed escrow agent, not the buyer's personal account.
When a Cash Offer Wins and When a Listing Wins
A cash offer tends to win when the home needs major repairs, you face a hard deadline like a relocation or estate settlement, the property is vacant or hard to show, or carrying costs eat into your equity each month.
A listing tends to win when the home is in good condition, the market favors sellers, you have time to wait, and the cash discount exceeds your carrying costs over the listing timeline.
The decision is not which method is better in the abstract, but which leaves more money in your pocket given your clock, condition, and county.
Florida Disclosures, Insurance, and Roof Rules Sellers Must Know
Florida sellers must disclose known defects that materially affect value, including water intrusion, roof damage, and permitted vs. unpermitted work. Use the state's property disclosure form and complete it honestly; a local real estate attorney can confirm what applies to your transaction.
What Florida Sellers Must Disclose
The property disclosure form is the starting point, not the whole obligation. Common items that must be disclosed when known:
- Roof condition and age, including active or prior leaks
- Water intrusion or flooding history, including prior insurance claims
- Structural defects and any repairs made without permits
- HVAC, plumbing, and electrical issues
Disclose in writing, keep a copy, and never rely on "the buyer should have seen it", an undisclosed known defect can surface after closing as a legal claim.
Insurance, Roof Age, and the Deal-Killers
Insurance matters more here than in most states. Insurers weigh roof age, material, and condition; a buyer who cannot get insurance cannot get a mortgage, so a roof near the end of its life can kill a contract.
Before you list:
- Get a roof inspection and document the age, material, and remaining life. A written report is worth more than a verbal estimate.
- Know the age of your water heater and HVAC. Buyers and insurers ask.
- Check for open permits on the property. Unpermitted work can stall a sale.
- Ask your own insurer what a new buyer would face. A quick call can reveal a problem before it becomes a contract issue.
Flood Zones, Storm Damage, and Documentation
Flood zones change buyer behavior and insurance cost. Check the FEMA flood map for your address and disclose any prior flood claims. If the home has been through a storm, keep the documentation:
- Insurance claim records and repair receipts
- Permits and inspection reports for post-storm repairs
- Photos of damage and completed work
- Elevation certificates if available, which can affect flood insurance pricing
Clean documentation moves buyers faster; gaps in the paper trail slow them down or send them walking.
County and City Differences Matter
Timelines and tactics are not uniform statewide: a beachside property and an inland one in the next county can face different insurance appetites, buyer pools, and days-on-market patterns. Pull local comps and absorption rates, the 66-day figure is a benchmark, not a promise for your block.
Your Fast-Sale Checklist and Next Steps
Here is the checklist we walk sellers through:
- Get a realistic market valuation, not a wish price
- Order a roof and HVAC inspection
- Complete the property disclosure form
- Decide: list, as-is, or cash offer
On scams: ask for proof of funds from a verified institution, never pay upfront fees to a "buyer," and confirm the entity through state records.
That is the honest version of how to sell house quickly in Florida: price sharp, fix what matters, stage well, and choose the method that fits your clock.
Selling fast in Florida is less about luck and more about sequencing the right decisions.
Frequently Asked Questions
How long does it usually take to sell a house in Florida?
Statewide averages show Florida homes spend about 66 days on the market, then roughly 34 more days to close after an offer is accepted, according to 2026 List With Clever data. That means a typical sale runs around 100 days from listing to closing. Individual timelines vary by county, price range, condition, and pricing strategy. Homes priced competitively and prepared well tend to move faster, while overpriced or heavily repaired properties can sit longer.
Is it faster to sell a house for cash?
Cash offers can close faster because they skip mortgage financing and appraisal contingencies. Some cash platforms advertise closings in as few as 7 days, though that is a service claim rather than a typical outcome. The tradeoff is that cash offers often come in below what a traditional listing might fetch. Compare a cash offer against your expected net from a listing, including agent commission, repairs, and carrying costs, before deciding which route gets you the best result.
What repairs should I make before selling my house?
Focus on items that affect safety, inspection results, and buyer perception: roof condition, HVAC function, water damage, plumbing leaks, and any active pest issues. Fresh paint, working light fixtures, and clean grout go a long way for little money. Skip major cosmetic overhauls like full kitchen remodels unless your agent confirms they will return more than they cost. In Florida, roof age and insurance eligibility matter more than most cosmetic upgrades, so address those first.
What should I do first to sell my house quickly?
Start with a pricing and condition assessment before you list. Get a comparative market analysis from a local agent who knows Volusia and Flagler county sales, then walk the property together to identify repairs and staging priorities. Confirm your roof age and insurance status, since Florida buyers and lenders scrutinize both. Once pricing and condition are set, line up marketing photos and showings. Getting these steps right before listing prevents the price cuts and delays that stretch out a sale.